Health Insurance Portability
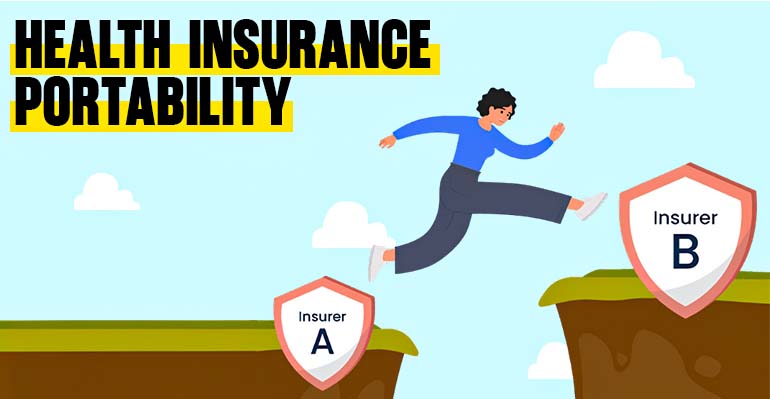
Health Insurance Portability
Health Insurance Portability in India allows you to switch your health insurance policy from one company to another without losing eligible continuity benefits. This process known as health insurance porting, is generally done when your existing policy is due for renewal. You can port your health insurance policy to another company if you are unhappy with the coverage, service, or other policy terms. During the health insurance portability process eligible waiting-period credits and certain accumulated benefits may carry forward, subject to applicable rules. Before you switch your health insurance company, compare the new policy’s coverage, exclusions, waiting periods, premium, and network hospitals.
How to Port Your Health Insurance Policy to another Company?
To port your health insurance policy first compare the new insurer’s coverage, exclusions, premium, waiting periods, and network hospitals. You can start the process online or contact with the policy hub team. Submit the required form and policy-related documents within the applicable renewal timeline. The new insurer will review your existing policy details and assess your request according to its terms and underwriting guidelines. During the porting process, eligible waiting-period credits and other continuity benefits may carry forward, subject to applicable rules. Once the request is accepted, your new policy will begin according to the agreed terms and conditions.
Rules for Health Insurance Portability and What Are Its Benefits?
Health Insurance Portability Rules allow policyholders to switch to another insurer at the time of renewal while retaining eligible continuity benefits from their existing policy. The request generally needs to be made within the applicable time period before renewal, and the new insurer can assess the application according to its underwriting guidelines. When you change your health insurance policy, eligible credits for the waiting period, including applicable continuity for pre-existing conditions, may carry forward as per the rules.
The main Health Insurance Portability Benefits include continuity of eligible waiting-period credits, the opportunity to choose a plan that better suits your coverage needs, and the flexibility to change insurers without starting your insurance journey from scratch.
Who Is Eligible for Health Insurance Portability and What Documents Are Needed?
If you have an active health insurance policy and want to switch to another insurer, you can generally request portability when your existing policy is due for renewal. The eligibility and acceptance of the request depend on applicable rules and the new insurer’s terms. It is also important to submit the request within the required time.
For the process, you may need your existing policy copy, renewal details, and identity and address proof, claim history, and other relevant policy information. A portability request form may also be required. Keeping your documents ready can make the switching process smoother and help avoid unnecessary delays.
How Does Family Floater Health Insurance Portability Work?
Family floater portability lets you move an existing family health insurance policy to another insurer when it is due for renewal. The new insurer reviews the family members covered, current sum insured, claims history, and other policy details before accepting the request. If approved, eligible waiting-period credits and continuity benefits can generally be carried forward according to the applicable rules. You may also choose a different level of coverage based on your family’s needs. Before switching, compare the new plan’s premium, exclusions, hospital network, coverage limits, and renewal terms to make sure it works well for everyone covered under the policy.
How Does Sum Insured Work During Health Insurance Portability?
Sum insured portability means the coverage amount under your existing health insurance policy is considered when you move to another insurer. For example, if your current policy has a ₹10 lakh sum insured, the eligible coverage and continuity benefits can be carried forward when the policy is ported, subject to applicable rules and the new insurer’s terms.
You can also request a higher sum insured when switching. However, the additional amount may be assessed separately by the new insurer and may have different waiting periods or conditions. This is important because the existing coverage and any increased portion may not always receive the same treatment.
Before making the switch, compare the new policy’s premium, coverage limits, exclusions, waiting periods, room-rent conditions, hospital network, and renewal terms. Also check how your existing benefits will be treated after porting. Understanding these details can help you choose coverage that continues to meet your healthcare needs without unexpected gaps.
Portability vs Migration: What Is the Difference?
Portability and migration both involve changing your health insurance arrangement, but they work differently. Here’s a simple comparison:
| Portability | Migration |
| Allows you to move your policy from one insurer to another. | Usually involves moving to another health insurance product offered by the same insurer. |
| Can help you retain eligible continuity benefits, such as waiting-period credits. | Benefits and terms depend on the new product and the insurer’s rules. |
| The new insurer reviews the request before accepting it. | The existing insurer handles the change within its product range. |
| Usually considered around policy renewal. | Timing and process depend on the insurer and product. |
| Useful when you want to change your health insurance provider. | Useful when you want to change your health insurance policy while staying with the same insurer. |
Simply portability means changing the insurer, while migration generally means changing the plan within the same insurer. Before making either change, check the coverage, exclusions, waiting periods, premium, and continuity benefits carefully.

5.0
Need advice from experts?
Don't guess your health cover, get expert guidance in one quick call.
How to Port Your Health Insurance Policy to another Company?
To port your health insurance policy first compare the new insurer’s coverage, exclusions, premium, waiting periods, and network hospitals. You can start the process online or contact with the policyhub team. Submit the required form and policy-related documents within the applicable renewal timeline. The new insurer will review your existing policy details and assess your request according to its terms and underwriting guidelines. During the porting process, eligible waiting-period credits and other continuity benefits may carry forward, subject to applicable rules. Once the request is accepted, your new policy will begin according to the agreed terms and conditions.
Rules for Health Insurance Portability and What Are Its Benefits?
Health Insurance Portability Rules allow policyholders to switch to another insurer at the time of renewal while retaining eligible continuity benefits from their existing policy. The request generally needs to be made within the applicable time period before renewal, and the new insurer can assess the application according to its underwriting guidelines. When you change your health insurance policy, eligible credits for the waiting period, including applicable continuity for pre-existing conditions, may carry forward as per the rules.
The main Health Insurance Portability Benefits include continuity of eligible waiting-period credits, the opportunity to choose a plan that better suits your coverage needs, and the flexibility to change insurers without starting your insurance journey from scratch.
Who Is Eligible for Health Insurance Portability and What Documents Are Needed?
If you have an active health insurance policy and want to switch to another insurer, you can generally request portability when your existing policy is due for renewal. The eligibility and acceptance of the request depend on applicable rules and the new insurer’s terms. It is also important to submit the request within the required time.
For the process, you may need your existing policy copy, renewal details, and identity and address proof, claim history, and other relevant policy information. A portability request form may also be required. Keeping your documents ready can make the switching process smoother and help avoid unnecessary delays.
How Does Family Floater Health Insurance Portability Work?
Family floater portability lets you move an existing family health insurance policy to another insurer when it is due for renewal. The new insurer reviews the family members covered, current sum insured, claims history, and other policy details before accepting the request. If approved, eligible waiting-period credits and continuity benefits can generally be carried forward according to the applicable rules. You may also choose a different level of coverage based on your family’s needs. Before switching, compare the new plan’s premium, exclusions, hospital network, coverage limits, and renewal terms to make sure it works well for everyone covered under the policy.
How Does Sum Insured Work During Health Insurance Portability?
Sum insured portability means the coverage amount under your existing health insurance policy is considered when you move to another insurer. For example, if your current policy has a ₹10 lakh sum insured, the eligible coverage and continuity benefits can be carried forward when the policy is ported, subject to applicable rules and the new insurer’s terms.
You can also request a higher sum insured when switching. However, the additional amount may be assessed separately by the new insurer and may have different waiting periods or conditions. This is important because the existing coverage and any increased portion may not always receive the same treatment.
Before making the switch, compare the new policy’s premium, coverage limits, exclusions, waiting periods, room-rent conditions, hospital network, and renewal terms. Also check how your existing benefits will be treated after porting. Understanding these details can help you choose coverage that continues to meet your healthcare needs without unexpected gaps.
Portability vs Migration: What Is the Difference?
Portability and migration both involve changing your health insurance arrangement, but they work differently. Here’s a simple comparison:
| Portability | Migration |
| Allows you to move your policy from one insurer to another. | Usually involves moving to another health insurance product offered by the same insurer. |
| Can help you retain eligible continuity benefits, such as waiting-period credits. | Benefits and terms depend on the new product and the insurer’s rules. |
| The new insurer reviews the request before accepting it. | The existing insurer handles the change within its product range. |
| Usually considered around policy renewal. | Timing and process depend on the insurer and product. |
| Useful when you want to change your health insurance provider. | Useful when you want to change your health insurance policy while staying with the same insurer. |
Simply portability means changing the insurer, while migration generally means changing the plan within the same insurer. Before making either change, check the coverage, exclusions, waiting periods, premium, and continuity benefits carefully.
How Does the Health Insurance Portability Process Work?
Check the new insurer’s coverage, exclusions, premium, waiting periods, and hospital network and other features that meets with your medical requirements.
Submit your request and required documents to the new insurer within the applicable portability deadline or 45 days before your existing policy renewal.
The new insurer reviews your existing policy and relevant medical and claim details.
During the health insurance porting process, eligible waiting-period credits and accumulated benefits may carry forward according to applicable rules.
If accepted, the new policy starts from the applicable renewal date under the new insurer’s terms.

5.0
Need advice from experts?
Too many plans, too much confusion? We'll simplify everything for you, completely FREE. 100% honest, 100% spam-free.
 Talk to an Advisor
 Talk to an Advisor